A $25,000 Penalty Taught Me That Forming an LLC Is the Easy Part

Tousif Akram
IRS CAA | Founder, FormLLC
A $25,000 Penalty Taught Me That Forming an LLC Is the Easy Part
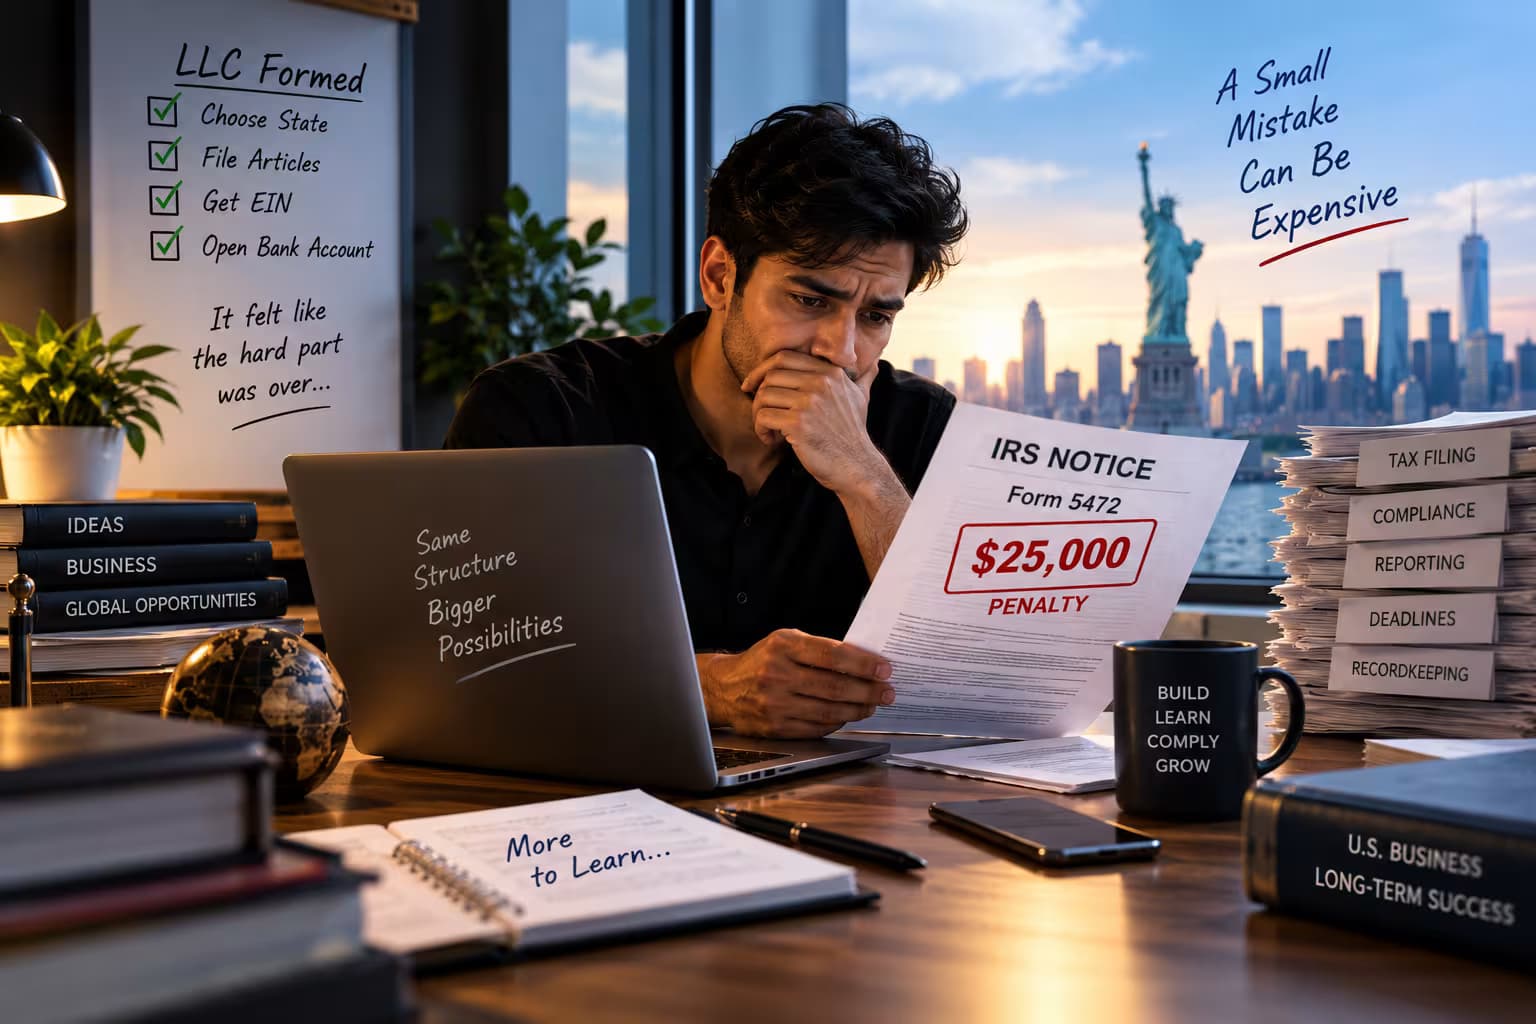
When I first started working with entrepreneurs who wanted to build businesses in the United States, I understood why forming an LLC felt like the biggest milestone. You choose a state, register the company, receive your formation documents, apply for an EIN, and suddenly you have a U.S. business. From the outside, it can feel like the difficult part is over.
But one of the biggest lessons of my journey came from a much more expensive reality: forming an LLC is often the easy part. Understanding what you are responsible for after formation is where things get serious.
The number that changed the way I looked at U.S. company formation was $25,000.
A failure to file a required Form 5472 can result in a $25,000 penalty for a reporting corporation. The IRS also states that an additional $25,000 continuation penalty can apply for each 30-day period after 90 days following an IRS notification if the failure continues.
That number is easy to read on an IRS page and move past. But when you understand what it represents, it changes the way you think about starting a U.S. business.
The lesson for me was not that entrepreneurs should be afraid of forming an LLC. It was that they need to understand that an LLC is a legal structure, not a complete compliance strategy.
What I Learned About Forming an LLC
Early in my journey, I used to think about company formation primarily as a starting point. An entrepreneur had an idea, wanted to operate internationally, needed a U.S. entity, and wanted to get the company created properly.
The obvious questions were which state to choose, how to register the LLC, how to get an EIN, and how to set up a business bank account.
Those questions are important, but they are only the beginning.
Once the company exists, the founder has a new set of responsibilities. Depending on the structure, ownership, activities, transactions, and state involved, there can be federal information reporting, tax filings, state-level requirements, banking requirements, recordkeeping, and other ongoing obligations.
The exact requirements are not the same for every business, which is precisely why assuming that every LLC follows the same checklist can create problems.
The $25,000 Form 5472 penalty made this lesson particularly clear to me.
The IRS identifies a foreign-owned U.S. disregarded entity as a reporting corporation for certain Form 5472 requirements. When applicable reportable transactions occur, the entity may have to file Form 5472 with a pro forma Form 1120.
That distinction is easy to miss if your entire understanding of a U.S. LLC is based on the registration process.
A U.S. LLC Can Look Simple From the Outside
For an international founder, the process can appear straightforward.
You form an LLC, receive your formation documents, obtain an EIN, open a bank account, and start operating. For a broader look at the formation process, you can also read our guide on For a broader look at the formation process, you can also read our guide on forming a U.S. LLC from India.
That is the version of the story that fits neatly into a checklist. Real businesses are more complicated.
A founder may put money into the company to fund its operations. The company may pay expenses. The owner may receive money from the business. The business may interact with related parties. There may be transactions that need to be documented or reported. There may also be state requirements that have nothing to do with federal tax filing.
The important point is that the company continuing to exist creates an ongoing administrative responsibility.
This is especially relevant for non-resident founders.
The IRS explains that a foreign-owned U.S. disregarded entity is treated as an entity separate from its owner for certain information-reporting requirements under Section 6038A.
That means the phrase "disregarded entity" should not be misunderstood as "nothing needs to be filed."
Those are very different concepts.
The $25,000 Number Is About Form 5472
Form 5472 is an information return used by certain 25% foreign-owned U.S. corporations and foreign corporations engaged in a U.S. trade or business when reportable transactions occur with related parties.
The IRS instructions specifically include foreign-owned U.S. disregarded entities within the definition of a reporting corporation for these purposes.
The penalty is what makes this requirement particularly important.
According to the IRS, a $25,000 penalty may apply when a reporting corporation fails to file Form 5472 when required, fails to file it in the prescribed manner, or fails to maintain the required records. The IRS also notes that a substantially incomplete Form 5472 can constitute a failure to file.
And the potential exposure does not necessarily stop at the initial $25,000.
If the IRS sends a notice about a failure to file Form 5472 and the required filing is not made within 90 days, the IRS states that an additional $25,000 continuation penalty can apply for each 30-day period after that 90-day period expires. The IRS says there is no maximum continuation penalty.
That is why I no longer think of compliance as something that can be left until the business becomes "big enough."
A company does not have to be a huge corporation for a reporting obligation to matter.
The Part Many New Founders Don't Understand
One of the biggest misunderstandings I see is the assumption that a company with little or no revenue has nothing to report.
Revenue and reporting obligations are not always the same thing.
A business can be small. It can have very few customers. It can be operated by one person. It can even be in its early stages.
But if the entity falls within a particular reporting requirement and has the relevant transactions, the filing obligation can still exist.
The IRS instructions for Form 5472 specifically identify transactions involving the formation, dissolution, acquisition, and disposition of a foreign-owned U.S. disregarded entity, including contributions to and distributions from the entity, as transactions that can be reportable under the rules.
That is one reason I tell founders that they should not ask only, "How much money did my business make?"
They should also ask, "What happened inside my business during the year, who was involved, and which reporting rules apply to those transactions?"
Those are very different questions.
Getting an EIN Does Not Finish the Process
Another lesson that became clear to me is that an EIN is important, but an EIN is not the finish line.
For a foreign-owned U.S. disregarded entity, an EIN can be required for certain federal filing purposes. The IRS's SS-4 instructions explain that a foreign-owned U.S. disregarded entity requesting an EIN for purposes of filing Form 5472 should identify that purpose when applying.
You can learn more about this process in our guide to EIN without SSN for non-residents.
The EIN is a tool.
It does not automatically tell you which returns you must file, which records you need to maintain, or what your ongoing responsibilities are.
This is something I wish more founders understood before they start operating.
Getting an EIN can feel like the final administrative step because it gives you a number associated with your business.
In reality, it can simply be another step in the process.
Banking Is Part of the Bigger Picture
The same principle applies to banking.
Many international founders think about a U.S. business bank account as one of the final steps after formation.
In reality, banking is connected to how the business operates, how money enters the company, how expenses are paid, and how transactions are documented.
For a non-resident founder, the banking process can also involve additional practical questions around identity verification, business documentation, ownership, source of funds, and the bank's own requirements.
I have written separately about U.S. bank accounts for non-residents because banking is one of the areas where founders often realize that having an LLC does not automatically give them access to every financial service they expect.
The company, the owner, the bank account, the payment processor, and the tax reporting are all connected parts of the same business.
Treating them as completely separate problems can make the overall process more confusing. Forming the Company Is Not the Same as Operating It
This is probably the biggest lesson I took away from the experience. There is a psychological difference between creating a company and operating a company.
Creating a company feels like an achievement. You receive the formation documents. You have a company name. You have a state filing. You may have an EIN. You can tell people that you have formed a U.S. business.
Operating the company is different.
Now you have to keep records.
You have to understand deadlines. You have to know what information needs to be reported. You have to separate personal and business activity appropriately. You have to understand how money moves through the business. You have to think about state and federal requirements.
You have to understand what happens when you pay yourself, contribute money, take money out, or transact with related parties. And if you are a non-resident founder, there can be additional cross-border considerations.
That is why I increasingly think of company formation as the beginning of a business journey rather than the destination.
The Mistake Is Thinking an LLC Is a Complete Business
An LLC is a legal structure. It is not customers. It is not revenue. It is not a bank account. It is not a tax strategy. It is not a compliance system.
And it certainly is not a guarantee that everything after formation will take care of itself. This sounds obvious when you say it that way, but the marketing around company formation can sometimes make the process feel much simpler.
"Form an LLC." "Get an EIN." "Open a bank account." "Start your business."
The reality is that each of those steps can raise additional questions.
Which state? What ownership structure? What tax classification? What federal filings apply? What state filings apply? Does the company have reportable transactions? What records should be maintained? When are filings due? What happens if you miss one?
Those questions are not designed to scare founders. They are designed to make them more aware of what they are actually building.
What the $25,000 Lesson Changed for Me The biggest change in my thinking was that I stopped viewing compliance as an afterthought.
I started seeing it as part of the product. If someone wants to build a company internationally, helping them form the company is only one part of helping them. They also need to understand what happens next. That means explaining the difference between formation and ongoing compliance.
It means making founders aware that certain filings can carry significant penalties. It means helping people understand that a small business can still have serious reporting obligations. And it means being honest about where professional tax or legal advice may be appropriate.
I don't think entrepreneurs need to become tax experts before starting a business. But they do need to know enough to recognize the questions they should be asking. That distinction is incredibly important.
The $25,000 Penalty Is Really a Lesson About Awareness
When people hear the phrase "$25,000 penalty," the natural reaction is to focus on the number. But the number isn't the real lesson. The real lesson is awareness.
A founder may spend weeks thinking about their company name.
They may compare states. They may spend time choosing a registered agent. They may research banking options.
They may think carefully about their website, branding, product, and customers. But none of those things replace understanding the compliance obligations attached to the business.
The formation process is visible. Compliance often happens quietly in the background. That is exactly why it can be overlooked.
You see the LLC certificate. You don't necessarily see the filing deadline coming. You see the EIN letter.
You don't necessarily see the reporting requirement that may follow. You see the bank account.
You don't necessarily think about how the transactions in that account need to be documented and reported. That difference between what is visible and what is important is one of the biggest lessons I have learned.
What I Tell Founders Now
Today, when someone tells me they want to form a U.S. LLC, I don't think only about getting the company registered.
I think about what they are actually trying to build.
Where do they live? Who owns the company? Where are their customers? How will money move through the business? What kind of transactions will they have? Will there be related-party transactions? What state requirements apply? What federal reporting requirements may apply? What happens after the company is formed?
Those questions create a much better starting point than simply asking which state has the cheapest LLC formation fee.
The right structure depends on the actual circumstances of the business. And the right compliance approach depends on the actual activities of the company. There is no universal checklist that can replace understanding the business itself.
What I Would Do Differently Today
If I were starting again, I would still form the company. I would still look for the right structure. I would still get the necessary identification numbers. I would still set up the banking and operational systems needed to run the business.But I would think about compliance from day one. I would maintain better records from the beginning. I would understand which transactions involve the owner or related parties. I would track important deadlines.
And I would ask questions before there was a problem rather than after. That is a much cheaper approach to entrepreneurship. The goal is not to become obsessed with paperwork.
The goal is to build the business in a way that allows you to focus on customers, products, growth, and opportunities without discovering an avoidable compliance problem later. The Real Cost of an LLC Is Not the Formation Fee
When someone asks me how much it costs to form an LLC, there is a straightforward answer: it depends on the state, the service provider, and what additional services the business needs.
But that is not the only cost founders should think about. There is also the cost of maintaining the company properly. There can be state fees. There can be tax preparation costs. There can be accounting costs.
There can be registered-agent requirements. There can be information-reporting requirements. There can be professional fees when a business has more complicated activities.
And, as the $25,000 Form 5472 penalty demonstrates, there can be substantial costs when a required filing is missed. The cheapest formation option is therefore not automatically the cheapest way to run a business.
Sometimes paying for proper guidance early is much less expensive than trying to fix a problem later. The Lesson I Carry Forward
The $25,000 figure stayed with me because it changed the way I think about entrepreneurship. When you are starting out, it is easy to focus on the exciting parts.
The company name. The website. The first customer. The first payment. The bank account. The idea. The growth.
But businesses also have a less visible side.
Records. Deadlines. Reporting. Compliance. Taxes. Documentation. Responsibilities.
Those things may not be exciting, but they are part of building something that can last.
My biggest lesson was simple: forming the LLC is easy compared with understanding how to operate it responsibly.
For founders, especially non-resident founders building businesses across borders, that distinction matters.
A U.S. LLC can be a useful business structure, but creating the entity is only the first step.
The real work begins when the company starts doing things. Money starts moving. Customers start paying.
Expenses start accumulating. Owners start contributing or withdrawing funds.
Related parties start interacting with the business. And reporting obligations begin to matter. That is when the company stops being a document and starts becoming a real business. Forming an LLC Is the Easy Part
If there is one thing I would want every new founder to understand before forming a U.S. LLC, it is this: Don't measure the difficulty of starting a business by how difficult it is to register the company.
Registration is a moment. Building and maintaining the business is a process.
The $25,000 Form 5472 penalty is a powerful reminder of that distinction. The IRS rules are specific, and whether a filing is required depends on the entity, ownership, transactions, and other facts. So before you ask, "How quickly can I form my LLC?" ask another question too:
"What will I be responsible for after I form it?" That question may not be as exciting. But it can be much more valuable.
Because forming the company gives you an entity. Understanding what comes next gives you a chance to build a business that can operate responsibly for years. The LLC is the beginning. Not the finish line.
This article is for general informational purposes only and does not constitute legal, tax, or financial advice. Tousif Akram and FormLLC are not a law firm or CPA firm. Consult a licensed professional for advice specific to your situation.
Ready to Form Your US LLC?
Free 30-minute consultation with no obligation and no sales pressure.
Book Free Call