Adding a Partner to a US LLC From India: Tax and Ownership Changes

Tousif Akram
IRS CAA | Founder, FormLLC
Adding a Partner to a US LLC From India: Tax and Ownership Changes
Bringing a new co-founder into a US business while operating from India can create opportunities for collaboration, growth, and international expansion. However, introducing a new LLC member involves more than changing ownership details. It can affect the operating agreement, decision-making authority, banking documentation, and federal tax classification. Understanding these changes before finalising the arrangement can help founders avoid misunderstandings and prepare for their responsibilities.
A US LLC with foreign members can work well for an international business when the ownership arrangement reflects how the founders intend to operate. Whether you are bringing in an Indian co-founder or another international business partner, review the legal, financial, and administrative implications before finalising the change. If you're still exploring your options, start with our US LLC formation guide for non-residents to understand the basics of establishing a US company.
What Changes When Adding a Partner to a US LLC?
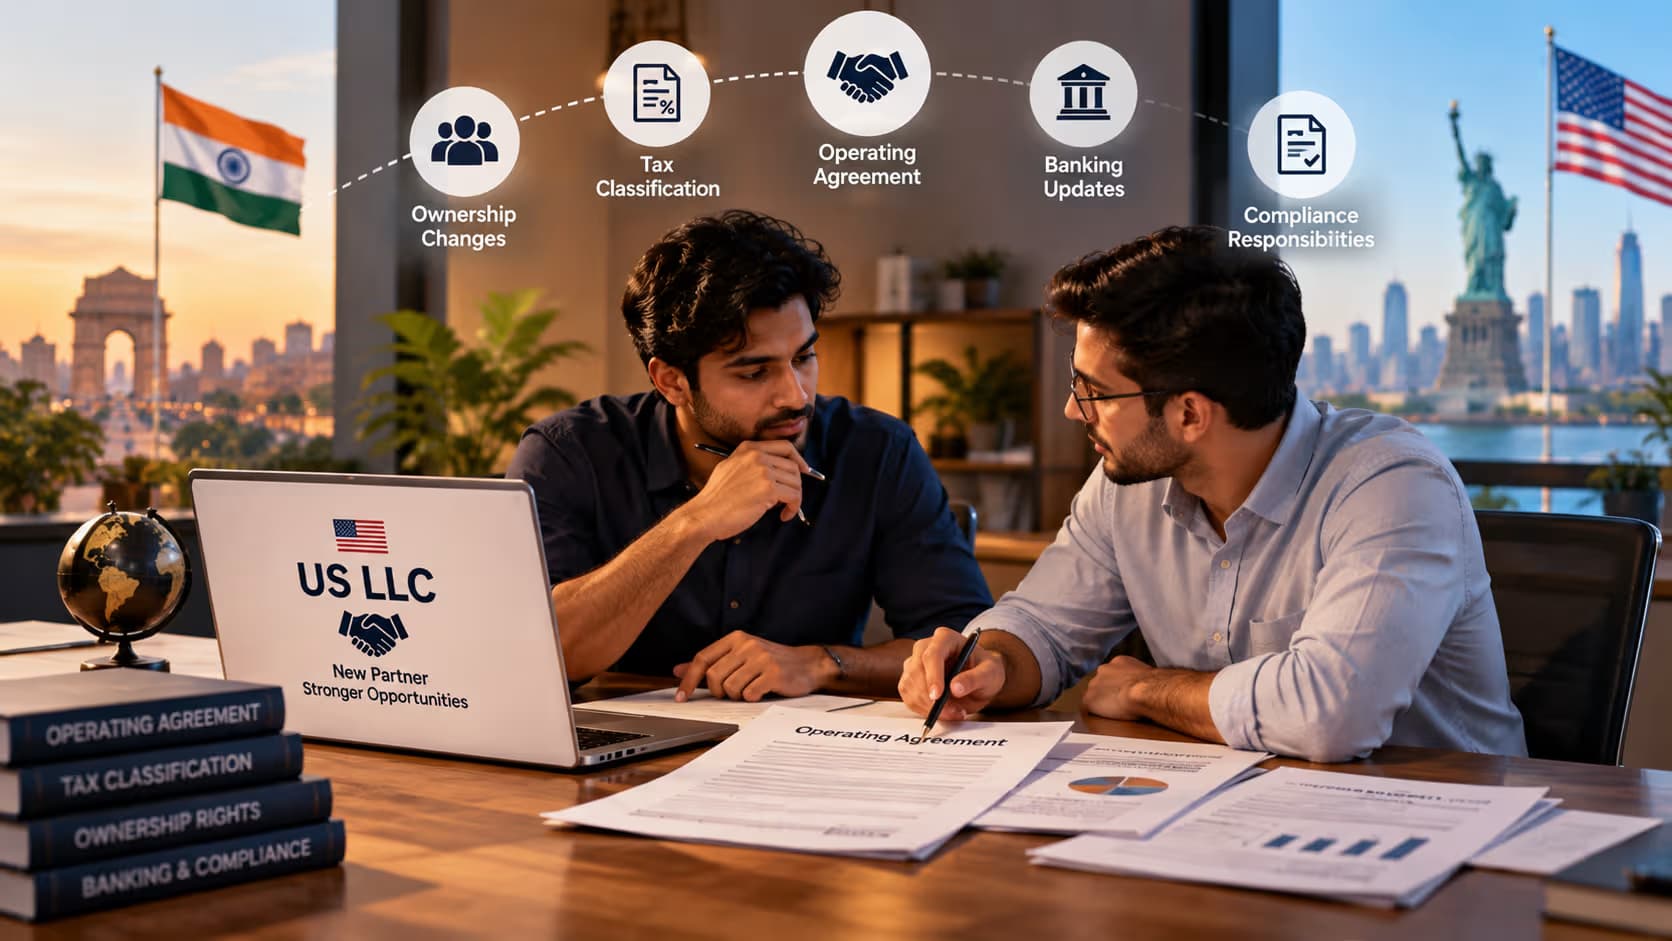
Admitting another member can affect several parts of an existing LLC, including its federal tax classification, ownership rights, operating agreement, financial accounts, and compliance responsibilities. The exact requirements depend on the company's existing structure, the formation state's laws, the nature of the ownership transaction, and any tax elections already in place.
Before proceeding, both founders should agree on their contributions, ownership percentages, responsibilities, and decision-making authority. Reviewing these details early can help ensure that the company's legal documents, financial records, and tax arrangements remain consistent.
1. Tax Implications of Adding a Partner to a US LLC
Understanding the Federal Tax Treatment of a Multi-Member LLC
One important change founders may overlook is the effect of a new member on federal tax classification. By default, the IRS generally treats a domestic LLC with one owner as a disregarded entity for federal income tax purposes. When a second member joins, the business is generally classified as a partnership unless it has elected corporate tax treatment or another special rule applies.
A partnership generally files Form 1065 and provides each partner with a Schedule K-1 reporting their share of the business's tax items. Depending on their individual circumstances, partners may have tax obligations even when the company retains its profits instead of distributing all available cash.
If your business was previously a foreign-owned single-member LLC, do not assume its existing tax reporting process will remain unchanged after admitting another owner. Review previous filings and seek professional advice about any reporting requirements associated with the transition.
Reviewing Tax Obligations Before the Ownership Change
Before finalising the change, review the effective date of the new membership, previous tax filings, and reporting obligations associated with the new classification. Existing tax elections and the nature of the transaction may also affect the outcome.
Working with a qualified tax professional who understands US taxation for non-US owners can help identify necessary changes and avoid preventable compliance problems. The appropriate reporting requirements depend on the company's tax classification and transactions, so review the relevant rules before deciding which forms apply.
2. Ownership Rules When Adding a Partner to a US LLC
Defining Ownership, Contributions, and Responsibilities
When you are the sole owner of an LLC, you generally have greater freedom to make business decisions independently. Once another member joins, the company needs clear rules explaining how decisions will be made and how responsibilities will be shared.
I recommend documenting each founder's ownership percentage, capital contribution, responsibilities, profit-and-loss allocation, and voting rights. Both partners should understand what they are contributing and what they can expect in return.
It is equally important to decide what happens if one founder wants to leave, stops contributing, disagrees with a major decision, or wants to sell their ownership interest. Addressing these situations in advance can help prevent misunderstandings when the business faces difficult decisions.
Preventing Disagreements Between International Co-Founders
For founders living in different countries, a clear operating agreement is especially important. A 50/50 ownership split may appear fair, but equal voting rights can create a deadlock if both partners disagree and neither has a mechanism for resolving the issue.
A well-drafted agreement should explain how major decisions are approved, how disputes are handled, and what happens when the founders cannot reach an agreement. These provisions become valuable when partners have different expectations, financial commitments, working schedules, or business priorities.
If you are admitting a member to an existing LLC, review the current operating agreement and follow its requirements for approving new members or amending the document. You should also check the rules of the formation state because the filings required for an ownership change can vary.
For more guidance on these documents, read our US LLC operating agreement guide for non-residents, which explains ownership, management, voting rights, profit distributions, and amendments.
3. Tax and Withholding Rules for Foreign Partners in a US LLC
Understanding US Tax Rules for Foreign Members
Having two non-US owners does not automatically mean that an LLC owes US income tax. The outcome depends on the business's activities, the nature and source of its income, applicable tax rules, and the circumstances of each owner.
However, if an LLC is taxed as a partnership and has effectively connected taxable income allocable to foreign partners, federal withholding requirements under Section 1446 may apply. The partnership may need to make withholding payments and file Forms 8804 and 8805, even if it does not distribute cash to its partners.
A foreign co-founder can introduce responsibilities that were not part of the company's previous compliance process. The precise obligations depend on the company's income and tax circumstances, so founders should assess them rather than rely on a generic checklist.
Planning Profit Allocation and Tax Reporting
Before the new member joins, determine how profits and losses will be allocated, what tax documentation each partner must provide, and who will coordinate the company's filings.
Founders should also consider how the business will manage tax-related cash requirements when taxable income is allocated to partners but profits remain in the company. Without advance planning, a partner could face a tax obligation without receiving a corresponding cash distribution.
For businesses operating across borders, understanding the relationship between ownership, income allocation, and compliance is an important part of building a sustainable company. Professional tax guidance is particularly valuable when the company's ownership structure or income sources change.
Foreign-owned businesses may also have separate information-reporting obligations depending on their classification and transactions. Our guide to Form 5472 for foreign-owned US LLCs explains when these requirements may apply. Keep in mind that a multi-member LLC taxed as a partnership does not automatically have the same Form 5472 obligations as a foreign-owned single-member disregarded entity.
4. Banking Changes When Adding a Partner to a US LLC
Updating Business Ownership and Account Information
A change in membership can affect your existing business bank account and payment processing arrangements. A bank or payment provider may request an updated operating agreement, information about the new owner, identity verification documents, or confirmation of who has authority to manage the account.
Do not assume that a new partner automatically receives access to the company's financial accounts. Account permissions and verification requirements depend on the provider's policies and the company's existing arrangements.
This is particularly important if your business relies on payment gateways to collect payments from international customers. Delays in updating ownership records or completing verification could disrupt normal operations.
Before making the change, contact your bank and payment provider to understand their requirements. Prepare the necessary documentation and confirm whether additional verification is needed before changing account access or management authority.
For a broader overview of banking requirements, read our guide on opening a US bank account as a non-resident LLC owner. It explains the documentation and verification processes non-resident founders may encounter.
Reviewing Your EIN and Federal Records
You should also review whether the ownership change affects the company's Employer Identification Number (EIN) requirements or other federal records. Whether a new EIN is needed depends on the transaction, the resulting tax classification, and the applicable IRS rules.
Do not assume that every LLC admitting another member must obtain a new EIN. Review the company's existing records and seek professional advice if the consequences are unclear.
5. State Requirements When Adding a Partner to a US LLC
Checking the LLC's Formation Documents
Admitting a new member may require amendments to internal company documents, updates to ownership records, or state filings, depending on the formation state's laws and the company's existing arrangements.
Start by reviewing the articles of organization, operating agreement, and any admission or transfer documents relevant to the transaction. Confirm whether the new member must formally agree to particular terms and whether the company needs to update any information filed with the state.
Not every ownership change requires the same filing process. The requirements can depend on the state, the type of transaction, and the information already on record.
Keeping Company Records Consistent
Once the new member is admitted, make sure the operating agreement, ownership records, tax documentation, and banking information accurately reflect the new arrangement. Consistent records can make future banking reviews, tax filings, and business decisions easier to manage.
Founders should also establish a process for maintaining these documents as the company grows. If ownership percentages, management responsibilities, or capital contributions change again, the relevant records should be updated accordingly.
My Advice to Founders Adding a Co-Founder
Before bringing a co-founder into your business, agree on the commercial terms, update the operating agreement, review the formation state's requirements, and assess the federal tax consequences. Make sure the relevant documentation and account updates are handled in the appropriate order.
For founders operating across borders, this should never be treated as a paperwork-only change. It can affect who controls the business, how profits are allocated, what the company must report, and how banks and payment providers verify ownership.
A US LLC can support a business with co-founders in different countries, but the structure should match the way those founders intend to work together. Clear ownership terms, appropriate tax planning, consistent records, and defined responsibilities provide a stronger foundation for long-term growth.
My rule is simple: agree on the partnership first, then update the company. When both founders understand what they own, what they contribute, and how decisions will be made, they can focus more confidently on building the business.
Frequently Asked Questions
Can I Add an Indian Partner to My US LLC?
Yes, an existing US LLC can generally admit an additional member who lives in India, subject to applicable state law, the company's operating agreement, and any relevant restrictions. The ownership change may also affect federal tax classification, reporting, and withholding obligations.
Does Adding a Second Member Change My LLC's Tax Classification?
Generally, yes, if the LLC is a domestic single-member LLC that has not elected corporate tax treatment. Adding a second member typically means the LLC is classified as a partnership for federal tax purposes. Existing tax elections and special circumstances should be reviewed before completing the change.
Do I Need a New EIN When Adding a Partner to My LLC?
Not necessarily. Whether a new EIN is required depends on the specific ownership transaction and the LLC's resulting tax classification. Review the applicable IRS rules and seek professional advice before applying for another EIN.
Does My Operating Agreement Need to Change When I Add a Partner?
You should review and generally update the operating agreement to reflect the new ownership arrangement and agreed terms. These may include ownership percentages, contributions, voting rights, profit allocation, management responsibilities, dispute resolution, and exit provisions.
Can Two Foreign Owners Operate a US LLC From Different Countries?
Yes, a US LLC can generally have members who live outside the United States. However, the founders need to understand applicable state requirements, federal tax rules, banking policies, and obligations arising from their business activities and tax residency.
Will Adding a Foreign Partner Create Additional US Tax Obligations?
It can. For example, a partnership with effectively connected taxable income allocable to foreign partners may have withholding and reporting obligations under Section 1446. The actual requirements depend on the company's income and circumstances, so professional tax guidance is advisable.
Can My Business Bank Account Be Affected by Adding a Member?
Yes. Banks and payment providers may require updated ownership information, identity verification, revised company documents, or changes to account access. Check the relevant provider's requirements before completing the ownership change.
This article is for general informational purposes only and does not constitute legal, tax, or financial advice. Tousif Akram and FormLLC are not a law firm or CPA firm. Consult a licensed professional for advice specific to your situation.
Ready to Form Your US LLC?
Free 30-minute consultation with no obligation and no sales pressure.
Book Free Call