Non resident llc us income tax treaty: The Talk I Have With Every SaaS Founder

Tousif Akram
IRS CAA | Founder, FormLLC
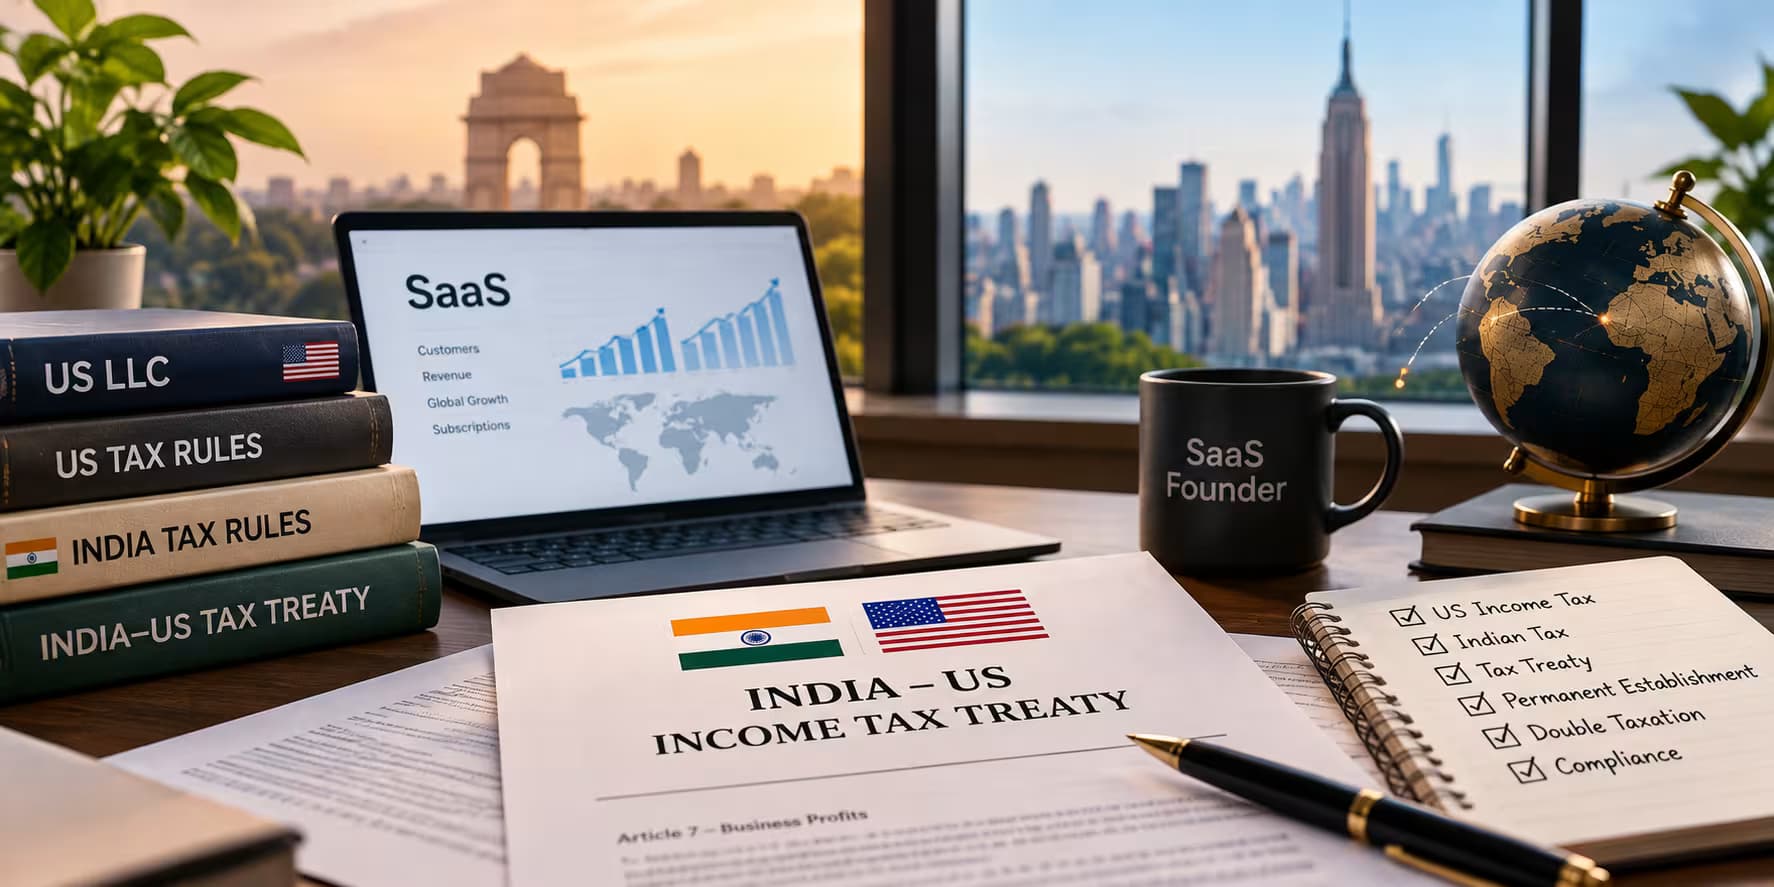
When Indian SaaS founders ask me about the non resident llc us income tax treaty, one question often comes up: “If my US LLC does not owe US income tax, does that mean I do not owe tax anywhere?” My answer is that these are two separate questions. The treaty may affect how certain income is taxed, but it does not automatically exempt an Indian founder from tax obligations in India.
Through my work helping international entrepreneurs establish US companies, I have learned that founders can focus so much on US formation and tax rules that they forget to consider their obligations in India. A US LLC may help you serve international customers, receive payments, and build a global business. However, forming a company in the United States does not automatically move your personal tax obligations out of India.
What Does the Non Resident LLC US Income Tax Treaty Actually Do?
The India–US tax treaty provides rules for determining how certain income is taxed when there is a connection to both countries. One important provision is Article 7, which addresses business profits. Broadly, it provides that business profits of an enterprise resident in one treaty country are generally taxable only in that country unless the enterprise carries on business in the other country through a permanent establishment there. If a permanent establishment exists, the other country may tax the profits attributable to it, subject to the treaty’s conditions.
For SaaS founders, applying these rules can involve several practical questions. Where is the business managed? Where are services performed? Do you have employees, an office, or other business operations in the United States? What are customers actually paying for: software access, licensing rights, professional services, or another product? The answers can affect how the income is characterized and which tax rules apply.
Simply having US customers or a US LLC does not, by itself, settle every tax question. Treaty benefits depend on the relevant treaty provisions and whether the person or entity earning the income qualifies to claim them. A US LLC’s tax classification can make the analysis more complicated, particularly when the LLC is treated differently for US and Indian tax purposes. Do not assume that registering a US LLC automatically makes its income exempt from US or Indian tax.
You can review the official India–US income tax treaty to understand its provisions. If you are still learning about the formation process, my guide to setting up a US LLC as a non-resident explains the business structure and its practical considerations.
Why No US Tax Can Still Mean Indian Tax
This is the point I want founders to understand before assuming their tax planning is complete. If you live in India and qualify as a resident and ordinarily resident for Indian tax purposes, your worldwide income may generally be taxable in India, subject to applicable law and any available treaty relief. If your Indian residential status is different, different rules may apply.
Imagine an Indian founder who runs a SaaS business through a US LLC, manages the business from India, and sells subscriptions to customers internationally. Even if the founder’s circumstances mean that no US federal income tax is due on certain business profits, that does not automatically make those profits exempt from Indian tax. The Indian tax treatment must be assessed separately based on the founder’s residential status, the nature of the income, the entity structure, and the applicable rules.
The distinction is important: US tax liability and Indian tax liability are not the same calculation. The United States applies its own tax rules, including rules concerning US business activities and effectively connected income. India applies its domestic tax laws, residential-status tests, and relevant treaty provisions. The way an LLC is treated in one country may not automatically determine how India treats the owner or the income.
That is why I encourage founders to ask two questions rather than one: “What do I owe in the United States?” and “How does India treat this income?” Understanding the non resident llc us income tax treaty requires looking at your Indian tax residency, your LLC’s US tax classification, the nature of your income, and whether you qualify for applicable treaty benefits. These factors should be reviewed together before you decide how to structure your SaaS business.
Why Your Indian Residential Status Matters
Your Indian tax residential status can influence whether India taxes only certain income or generally considers your worldwide income. It should be determined under the applicable Indian rules for the relevant financial year rather than assumed solely from citizenship, the location of your LLC, or where your customers are based.
For this reason, SaaS founders should assess their personal tax position separately from their company’s US compliance requirements. If you are reviewing annual US reporting obligations as well, read this guide to non-resident US LLC tax filing and confirm which requirements apply to your particular LLC.
Can You Avoid Double Taxation?
The India–US tax treaty and domestic tax rules may provide mechanisms for relief from double taxation, including foreign tax credits where the relevant conditions are met. However, relief from double taxation is not the same as an automatic exemption from tax. You must first establish how the income is treated in each country and whether the requirements for relief are satisfied.
If you have paid qualifying US income tax on income that is also taxable in India, you may be able to claim a foreign tax credit under the applicable rules, subject to limitations, documentation, and procedural requirements. India has procedures for claiming foreign tax credit, including Form 67 in applicable cases. Review the Indian Income Tax Department’s Form 67 guidance for relevant filing requirements.
However, if no US income tax was paid on the income, there may be no US income tax amount available to claim as a credit for that income. You would still need to determine whether the income is taxable in India. The exact outcome depends on the type of income, your residential status, the relevant treaty provisions, and the tax year involved.
This is why I advise founders not to build their tax planning around the assumption that a treaty eliminates all tax obligations. A treaty may allocate taxing rights or provide relief in qualifying circumstances, but it does not replace the need to review domestic law and applicable reporting requirements in both countries.
What I Tell SaaS Founders Before They Form a US LLC
My advice is to consider the whole business structure before focusing only on US filings. Start by confirming how your LLC is classified for US tax purposes, understanding where the business is managed and operated, and establishing your Indian tax residential status. Then review the nature of your SaaS revenue and whether the relevant treaty provisions apply to your specific circumstances.
It is also important to distinguish between obtaining a company identification number, meeting annual LLC reporting requirements, and satisfying personal tax obligations. These are different responsibilities. If you are still working through the initial setup, my guide on getting an EIN without an SSN as a non-resident explains one part of the process. Obtaining an EIN, however, does not determine how your income will be taxed in India or establish eligibility for treaty benefits.
A US LLC can be a useful structure for an international business, but it is not a shortcut around tax rules in your home country. Company formation, US compliance, treaty eligibility, and Indian personal or business tax obligations are connected issues that need to be reviewed together.
The conversation I want every founder to have early is simple: do not stop at asking whether your LLC owes US tax. Ask how the income is treated in every country that may have a legitimate taxing claim, what reporting obligations apply, and whether any available treaty relief can be claimed.
The goal is not just to form a US company. It is to build a global business with a clear understanding of its tax obligations on both sides.
Frequently Asked Questions
Does the India–US tax treaty mean my US LLC income is tax-free in India?
No. The treaty does not automatically make income earned through a US LLC tax-free in India. Your Indian residential status, the nature of the income, the LLC’s tax classification, and the relevant treaty provisions all matter. You should assess the Indian tax treatment separately from the US tax position.
Does having a US LLC mean I must pay tax in the United States?
Not necessarily. The answer depends on the LLC’s classification, its activities, the nature and source of its income, and other applicable rules. Even when no US federal income tax is due, certain reporting or state-level compliance requirements may still apply.
Can an Indian SaaS founder claim a foreign tax credit for US taxes paid?
A foreign tax credit may be available when the applicable requirements are satisfied. Eligibility, the amount of credit, supporting documentation, and filing procedures must be checked under the relevant Indian rules and treaty provisions. Form 67 may be required in applicable cases.
Does managing my US LLC from India affect my tax position?
It can be relevant. Where a business is managed and operated, the owner’s residential status, the nature of business activities, and the applicable domestic and treaty rules may all affect the analysis. The location of the LLC’s registration alone does not resolve every tax question.
Should I consult a tax adviser in India or the United States?
For a cross-border structure, it is often sensible to work with qualified advisers who understand both US and Indian tax rules. This can help you assess the LLC’s classification, personal tax obligations, treaty eligibility, filing requirements, and any potential double-taxation relief.
Final Thoughts
The India–US tax treaty is an important part of understanding cross-border business taxation, but it should not be treated as a blanket exemption from tax. The difference between US tax liability and Indian tax liability matters, particularly for SaaS founders who live in India while operating a US LLC.
Before relying on a treaty position, confirm your residential status, understand how the LLC is classified in each relevant jurisdiction, identify the nature of your income, and review the rules that apply to your circumstances. A well-planned international business structure should account for compliance in both countries from the beginning.
*This article provides general educational information, not individualized US or Indian tax advice. Treaty eligibility and tax treatment depend on the facts, entity classification, income type, residential status, and applicable law. Consult qualified tax advisers familiar with both jurisdictions before relying on a treaty position.*
This article is for general informational purposes only and does not constitute legal, tax, or financial advice. Tousif Akram and FormLLC are not a law firm or CPA firm. Consult a licensed professional for advice specific to your situation.
Ready to Form Your US LLC?
Free 30-minute consultation with no obligation and no sales pressure.
Book Free Call